

In the third quarter, markets absorbed higher rates, rising oil prices, and renewed inflation concerns, and continued to advance. Strong earnings, consumer spending, and sustained AI-related investment kept growth intact, although that CAPEX may also be reinforcing a higher-for-longer rate environment. The result for investors is a broader opportunity set, highlighted by improved income in bonds, continued support for risk assets, and a greater premium on selectivity.
Total return, annual averages over period shown, 2011-June 2026
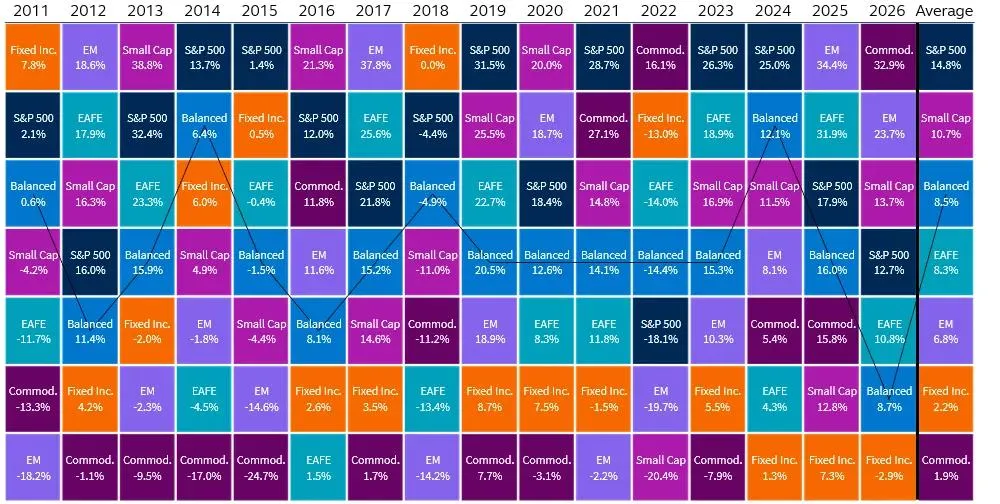
Source: Clearnomics, Principal Asset Management. Asset classes are represented by the S&P 500, MSCI EM, MSCI EAFE, Russell 2000, iShares Core U.S. Bond Aggregate and Bloomberg Commodity Index. The Balanced Portfolio is a hypothetical 60/40 portfolio consisting of 40% U.S. Large Cap, 5% Small Cap, 10% International Developed Equities, 5% Emerging Market Equities, 35% U.S. Bonds, and 5% Commodities. Data as of September 30, 2026.
The third quarter gave investors plenty of reasons to be cautious, and markets continued to climb anyway. Despite a weak September, the third quarter saw the S&P 500 gain 2.3%, and the Nasdaq composite rise 2.8%, leaving both near record territory. Strong earnings, resilient growth, and continued investment in AI infrastructure helped offset higher rates and renewed inflation concerns.
The quarter’s most notable moves were in energy and bonds. The Energy sector led the S&P 500 as conflict in the Middle East pushed oil prices toward $100/barrel. In fixed income, persistent inflation and steady economic activity drove 5-, 10-, and 30-year Treasury yields above 5% for the first time in roughly two decades.
Economic signals were mixed in 3Q but point to continued resilience. Consumer confidence fell to a 12-year low, yet second-quarter GDP growth was revised up to 2.2%, supported by consumer spending. And while inflation remains above the Fed’s target, AI-related capital investment is potentially adding a structural source of demand and reinforcing a higher-for-longer rate environment.
For investors, the quarter leaves a more balanced opportunity set. Higher yields have improved the income available in bonds, while strong earnings and continued AI-related investment remain supportive of equities. Together, those dynamics suggest an environment where resilience can persist, even as elevated rates and inflation continue to demand greater selectivity.
©2026 Principal Financial Services, Inc.,
711 High Street, Des Moines, Iowa 50392
|